Venn vs Loop (2026): The Best Bank Account for a Canadian Startup
Disclosure: this post contains affiliate links. If you sign up through one, we may earn a commission at no extra cost to you. We only recommend tools a CPA has reviewed from the vendor's own pages.
Venn or Loop: which is the better business account for a Canadian startup?
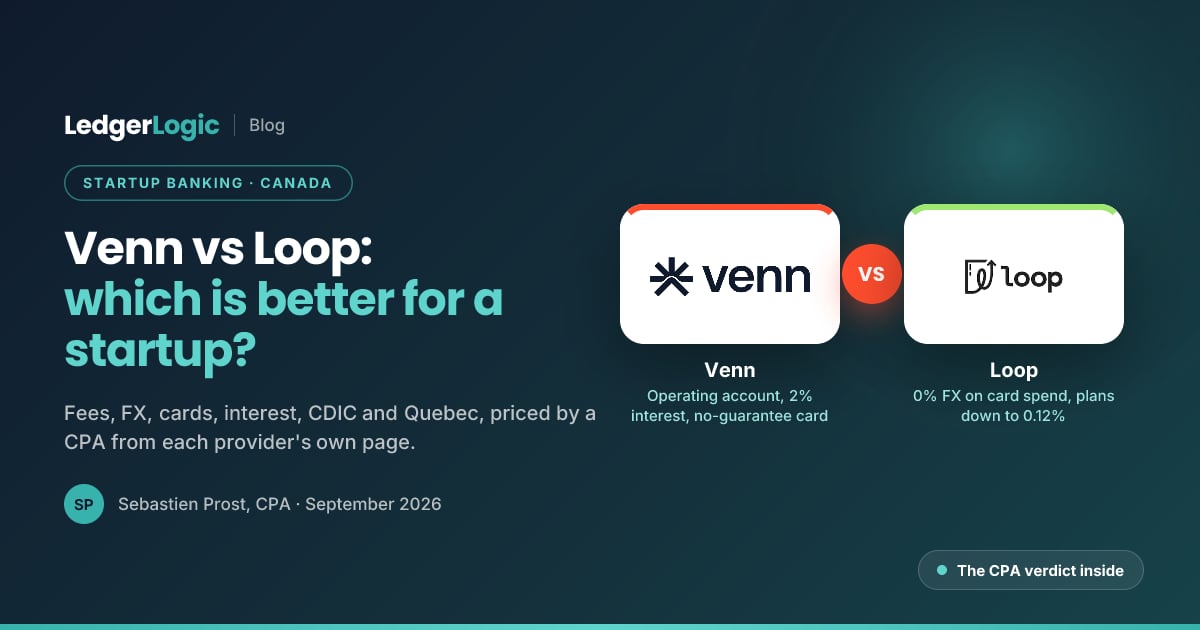
For most startups outside Quebec, Venn (formerly Vault): $0 a month, a US-domiciled USD account for ACH, FX at 0.45% on the free plan, 2% interest on CAD and USD, a Mastercard charge card with no personal guarantee and 1% cashback on up to $5,000 of card spend a month on the free plan, and balances at Bank of Montreal with CDIC eligibility. Loop wins for volume converters willing to pay $79 or $299 a month for 0.27% or 0.12%; its Visa carries 0% FX on held USD, EUR or GBP, as Venn's card does when the matching balance covers the purchase. Neither is a bank or serves cash. Verified at venn.ca and bankonloop.com, September 2026.
At a Glance
Venn and Loop are the two Canadian fintechs a startup usually shortlists once it decides a Big 5 branch account is too slow and too expensive. Both are Toronto-built, both hold CAD, USD, GBP and EUR, both issue corporate cards, and both connect to Xero and QuickBooks. They are not the same product. Venn (the company formerly called Vault) is built to be your operating account; Loop is built around FX and cross-border card spend. This comparison prices both from their own pricing pages, read on 2 September 2026, by a CPA.
Last updated: September 2026. Every fee, rate and regulatory statement below was verified at venn.ca and bankonloop.com on 2 September 2026, and the Venn figures and Loop's deposit protection again on 25 September 2026. Vault rebranded to Venn in February 2025; this page keeps its original address so earlier links still work.
Open the account we recommend first
Venn holds CAD, USD, GBP and EUR with no monthly fee, a US-domiciled USD account for ACH, 0.45% FX, 2% interest on CAD and USD balances, and a Mastercard charge card with no personal guarantee. Corporations and registered sole proprietorships, outside Quebec; registered corporations earn up to $500 through our link.
The Short Answer for a Canadian Startup
Venn is the better primary account for most startups outside Quebec: $0 a month, a US-domiciled USD account for ACH, FX at 0.45% on the free plan, 2% interest on CAD and USD balances, a Mastercard charge card with no personal guarantee and 1% cashback on up to $5,000 of card spend a month on the free plan ($25,000 on Plus, uncapped on Pro), bill pay with single-step approvals (multi-step on Pro), and balances held at Bank of Montreal with CDIC eligibility. Loop wins for a business that wants a credit card or converts heavily: its paid plans drive the conversion margin down to 0.27% and 0.12%, and, counting monthly plan fees at 1.41 Canadian dollars to the US dollar, Loop Plus is the cheapest way to convert between about US$34,600 and US$74,500 a month and Loop Power above about US$108,600, with Venn Pro cheapest in between. Both cards spend a held USD, EUR or GBP balance at 0% FX. Loop does not name the institution holding its CAD balances, though it says eligible CAD deposits are held in trust at CDIC member institutions, and it publishes no interest rate. If you also hold or collect currencies beyond those four, or you are in Quebec, Airwallex enters the picture; see the section below.
Venn vs Loop: Fees and Features Side by Side
| Feature | Venn | Loop |
|---|---|---|
| Monthly fee | $0 Essentials; $40 Plus; $100 Pro | $0 Basic; $79 Loop Plus; $299 Loop Power |
| FX margin | 0.45% / 0.35% / 0.25% by plan | 0.47% / 0.27% / 0.12% by plan |
| Card FX | Card purchases in USD, GBP or EUR draw on the matching balance first; otherwise converted from CAD at the plan rate | 0% FX on card purchases in CAD, USD, EUR and GBP, settled from the matching balance |
| Currencies held | CAD, USD, GBP, EUR (30-plus currencies for sending) | CAD plus free USD, EUR and GBP accounts |
| US account details for ACH | Yes, US-domiciled account with a US routing number | Yes, USD accounts provided by Lincoln Savings Bank |
| International wires | $10 / $8 / $6 by plan | Free wire transfers on every plan, per the pricing page |
| Interest on balances | 2% on CAD and USD; 2.75% CAD and 3% USD on net-new balances added by October 15, 2026 (promotion) | None advertised |
| Corporate card | Mastercard charge card, Peoples Trust, no personal credit check or guarantee, 1% cashback (capped at $5,000 monthly spend on Essentials) | Loop Global Visa, Equitable Bank; 2 physical and 20 virtual cards on Basic; points on CAD spend (2x on paid plans) |
| Bill pay and approvals | Included; single-step approvals on Essentials and Plus, multi-step on Pro | ACH/EFT billing at 0.5% + $1 per invoice on Basic, 0.25% + $1 on Plus, $1 on Power |
| Deposit protection | Balances held at Bank of Montreal, CDIC-eligible up to $100,000 per category | USD accounts at Lincoln Savings Bank (FDIC); eligible CAD deposits held in trust at CDIC members, protected up to $100,000 (institution not named) |
| Regulation | FINTRAC MSB M22941967; registered payment service provider with the Bank of Canada | FINTRAC-registered; SOC 2 Type II audited; not a bank |
| Quebec | Not available to Quebec businesses | Not stated on the pricing page |
| Accounting integrations | Xero and QuickBooks Online (direct); NetSuite only as a custom ERP add-on on the Custom plan | QuickBooks Online, Xero and Wave via direct API |
Venn: The Operating Account Built for Canadian Startups
Venn is the account we recommend first for incorporated Canadian businesses outside Quebec. The Essentials plan is $0 a month with CAD, USD, GBP and EUR accounts; the USD account is US-domiciled with a real US routing number, so American customers pay you by ACH like a domestic vendor and Stripe or Shopify payouts land without a wire. Conversions cost 0.45% on Essentials, 0.35% on Plus ($40 a month) and 0.25% on Pro ($100 a month), and international wires are $10, $8 and $6 respectively. Balances earn 2% on CAD and USD on every plan, promoted to 2.75% on CAD and 3% on USD for net-new money added by October 15, 2026. The Venn Mastercard charge card, issued by Peoples Trust, needs no personal credit check or guarantee and pays 1% cashback (capped at $5,000 of monthly spend on Essentials, $25,000 on Plus, unlimited on Pro). Bill pay is built in, with single-step approvals on Essentials and Plus and multi-step approvals on Pro, and Xero and QuickBooks Online connect directly (NetSuite and other ERPs are a custom add-on on the Custom plan). Venn Software Inc. is registered with FINTRAC (M22941967) and with the Bank of Canada as a payment service provider, and balances are held at Bank of Montreal, a CDIC member. Two limits: Venn is not available to businesses in Quebec, and there is no cash or cheque deposit. Registered corporations get up to $500 through our partner link, tied to card spend in the first 90 days; sole proprietors can open the account but do not get the bonus. Open a Venn account or read the bonus terms first.
Loop: Built Around FX and Cross-Border Card Spend
Loop, from Loop Financial Inc. in Toronto, has been building products for Canadian businesses since 2015 and started life as Lending Loop. Its pitch is the card: the Loop Global Visa, a credit card issued by Equitable Bank, charges 0% FX on purchases in CAD, USD, EUR or GBP because each charge settles from the matching currency balance (Venn's card does the same with a held USD, GBP or EUR balance), and every plan includes free USD, EUR and GBP accounts, with the USD account provided by Lincoln Savings Bank, an FDIC member. Converting between your own balances costs 0.47% on the free Basic plan, 0.27% on Loop Plus ($79 a month, or $71 billed annually) and 0.12% on Loop Power ($299 a month, or $250 annually), so a business converting real volume can beat Venn's best rate by paying for a plan. Basic includes 2 physical and 20 virtual cards earning points on CAD spend; Plus and Power add more cards and 2x points. Collecting payments by ACH or EFT is priced per invoice: 0.5% plus $1 on Basic, 0.25% plus $1 on Plus, a flat $1 on Power, and wire transfers are free on every plan. QuickBooks Online, Xero and Wave connect through Loop's direct API rather than a screen-scraped bank feed. Loop is not a bank, is FINTRAC-registered and SOC 2 Type II audited, and keeps client funds separate from its own; it says eligible CAD deposits held in trust at CDIC member institutions are protected up to $100,000, though it does not name the institution, and it advertises no interest on balances. E-commerce sellers who want a credit card for heavy spending on US ad platforms and overseas suppliers, or who convert enough to pay for a plan, are the natural fit.
The FX Math for a Startup
Take a startup converting US$10,000 a month into CAD. At a typical bank spread of 2.5% that is about US$3,000 a year. On Venn Essentials at 0.45% it is about US$540; on Loop Basic at 0.47% about US$565. The two free plans are within US$25 of each other. Card spending does not separate them either: a team that pays US$10,000 a month of SaaS and ad spend on a card pays nothing in FX at Loop, because the card settles from the USD balance, and nothing at Venn while its USD balance covers the charge. The gap stays narrow at volume: converting US$100,000 a month costs roughly CA$5,430 a year on Venn Pro (0.25% plus $1,200 in plan fees), CA$5,520 on Loop Plus (0.27% plus $948) and CA$5,620 on Loop Power (0.12% plus $3,588), at 1.41 Canadian dollars to the US dollar; Power only pulls ahead of Venn Pro above about US$108,600 a month. Run your own numbers; the plan fee decides it.
Which Is the Better Bank Account for a Canadian Startup?
For a newly incorporated company that needs one account to run payroll, pay suppliers, collect from US customers and give founders a card, Venn is the stronger default: the charge card needs no personal guarantee, interest accrues on idle cash, bill pay is included, and CDIC eligibility through Bank of Montreal answers the question every founder's accountant asks. Loop is the pick when the business wants a credit card for heavy spending across currencies, or when conversion volume justifies a paid plan for the lower margin. Neither takes cash or cheques or lends, so a startup that raises a line of credit or handles cash still keeps a bank relationship; see the wider Canadian business bank account comparison for how RBC and TD fit beside them.
Where Airwallex Fits
Both Venn and Loop hold only four currencies. A startup collecting in Australian or Singapore dollars, or selling into ten Amazon marketplaces, outgrows them, and that is Airwallex's lane: local account details in 20-plus currencies on a $0 plan, FX at 0.5% on major currencies, free batch payouts to 120-plus countries, unlimited Visa cards with 0% foreign fees, and a Revenu Québec MSB licence, which makes it the option for a Quebec startup that Venn cannot serve. It is not a bank either, and it pays no interest on Canadian balances. The pairing we recommend most often is Venn as the operating account and Airwallex for the currencies beyond CAD, USD, GBP and EUR; the multi-currency account guide covers the full field including Wise.
What About Quebec?
Venn's pricing page states plainly that it is not available to businesses in Quebec. Loop's pricing page says nothing either way, so confirm at signup. Airwallex and Wise both hold Revenu Québec money-services-business licences and are open to Quebec companies, and the Big 5 banks serve the province directly.
Opening and Switching
Both open online in minutes with your articles of incorporation, business number and director ID, and most accounts are live within a day or two. Keep the old bank account open for a month while pre-authorised debits and CRA remittances move over, connect the new account to Xero or QuickBooks so the bank feed starts on day one, and set each currency balance up as its own bank account in the ledger so FX gains and losses are recorded properly at year-end.
Frequently Asked Questions
- Is Venn the same as Vault?
- Yes. Vault, the Toronto business-banking fintech launched in 2023, rebranded to Venn in February 2025 alongside a $21.5 million Series A round, as reported by BetaKit. The product, the CAD, USD, GBP and EUR accounts and the team are the same; only the name changed. Venn Software Inc. is the legal entity registered with FINTRAC.
- Venn or Loop: which is cheaper for a Canadian startup?
- On the free plans they are nearly identical for conversions: 0.45% at Venn, 0.47% at Loop, about US$25 a year apart on US$10,000 a month. Card spending in USD, EUR or GBP carries no FX at either when the matching balance covers it, and Loop's paid plans reach 0.12%. Venn is cheaper overall for a business that wants interest on balances, included bill pay and a no-guarantee charge card without paying a monthly fee.
- Does Venn or Loop pay interest on business balances?
- Venn pays 2% on CAD and USD balances on every plan, promoted to 2.75% on CAD and 3% on USD for net-new money added by October 15, 2026. Loop does not advertise interest on its pricing page.
- Are Venn and Loop CDIC insured?
- Venn balances are held at Bank of Montreal, a CDIC member, and are eligible for CDIC insurance up to $100,000 per deposit category. Loop's USD accounts are provided by Lincoln Savings Bank, an FDIC member; its pricing page says eligible CAD deposits held in trust at CDIC member institutions are protected up to $100,000 per depositor, per insurance category, without naming the institution. Neither company is itself a bank.
- Can a sole proprietor open Venn or Loop?
- Venn's signup lists sole proprietor as a company type and accepts registered sole proprietorships with a business number and registration document. Loop serves businesses; confirm your structure at signup. Neither serves personal accounts. Venn's signup bonus is for registered corporations only.
- Do Venn and Loop work in Quebec?
- Venn states it is not available to businesses in Quebec. Loop's pricing page does not address Quebec, so confirm before applying. Airwallex and Wise Business both hold Revenu Québec MSB licences and are open to Quebec businesses.
- Do I need a personal guarantee for the Venn or Loop card?
- Venn states there is no personal credit check or guarantee for its Mastercard charge card, which is issued by Peoples Trust. Loop's Global Visa is issued by Equitable Bank; the card terms and any credit assessment are set during Loop's application, and its pricing page does not state a guarantee requirement either way.
- Can I use Venn and Loop together?
- Yes. Some card-heavy businesses run Venn as the operating account for payroll, remittances, interest and bill pay, and Loop for a credit card or for cheaper bulk conversion on its paid plans. Each balance is simply another bank account in Xero or QuickBooks. Most startups do not need both; pick the one that matches where your money moves.
Still deciding? See the full Venn review, the Float versus Venn comparison for card-first alternatives, and our business bill pay guide if payables are the job.
Sebastien ProstCPA, Ex-CRA
Licensed CPA with 10+ years of experience, including work with the Canada Revenue Agency. Founder of LedgerLogic, a cloud accounting firm serving Canadian SMEs. Xero Certified Advisor.