Disclosure: this post contains affiliate links. If you sign up through one, we may earn a commission at no extra cost to you. We only recommend tools we use with our own clients.
Which multi-currency business account is best in Canada?
The best multi-currency business account in Canada for most businesses outside Quebec is Venn: no monthly fee, CAD, USD, GBP and EUR with a US-domiciled USD account for ACH, FX at 0.45% on the free plan (vs about 2.5% at the banks), and 2% interest on CAD and USD balances. Airwallex is the pick once you deal in more than four currencies or pay overseas suppliers: local details in 20-plus currencies, 0.5% FX, no monthly fee, and licensed in Quebec. Wise Business has the cheapest conversions (from 0.19%) after a one-time 55 CAD setup. Verified at each provider's pricing page, September 2026.
At a Glance
If your Canadian business bills in US dollars, pays overseas suppliers, or sells into the US, a plain CAD chequing account quietly costs you thousands a year in FX spreads. A multi-currency business account fixes that, and in 2026 the best options are fintechs, not banks. Here are the five accounts worth considering, priced from each provider's own published fees by a CPA who runs client money through them.
Last updated: September 2026. Every fee and rate below was re-verified on each provider's Canadian pricing page on 2 September 2026.
Stop Paying the Bank’s FX Spread
Venn holds CAD, USD, GBP and EUR in one no-fee account with a US-domiciled USD account for ACH, FX from 0.45%, and 2% interest on CAD and USD balances. Corporations and registered sole proprietorships, outside Quebec. Opening takes about 10 minutes online.
The Five Options Compared
| Account | Monthly fee | FX cost | Local account details | Best for |
|---|---|---|---|---|
| Venn | $0 (Essentials) | 0.45%, down to 0.25% on paid plans | CAD, USD (US-domiciled), GBP, EUR | Primary operating account: interest, cards, bill pay. Not in Quebec |
| Airwallex | $0 (Explore) | 0.5% on major currencies, 1% on others | 20+ currencies | Many currencies, overseas suppliers, marketplace payouts. Licensed in Quebec |
| Wise Business | $0 after a one-time 55 CAD setup | From 0.19% | 22 currencies | Cheapest pure conversion, transparent transfers |
| Loop | $0 (Basic); Plus $79 | 0.47% on Basic, 0.27% on Plus; 0% on card purchases in CAD, USD, EUR, GBP | USD, EUR, GBP accounts, free | Card-heavy spending across currencies |
| Big 5 USD account (RBC) | $9 USD, waived above a $2,500 USD balance | Typically 2.5% or more built into the rate | Canadian-domiciled USD only | Cash deposits, lending relationships |
Venn: The Best All-Round Multi-Currency Account
Venn holds CAD, USD, GBP, and EUR in one no-fee account, and its US dollar account is US-domiciled with a real US routing number, so American customers pay you by ACH like a domestic vendor, with no wire fees and no forced conversion. Conversions cost 0.45% on the free Essentials plan, 0.35% on Plus ($40 a month) and 0.25% on Pro ($100 a month), against roughly 2.5% at a branch bank. International wires are $10 on Essentials. Balances earn 2% on CAD and USD on every plan, with a promoted rate of up to 2.75% on CAD and 3.5% on USD for a limited time as of September 2026. The same account issues corporate cards with 1% cashback (capped at $5,000 of monthly spend on Essentials) and runs bill payments. Balances are held at Bank of Montreal, a CDIC member. Corporations and registered sole proprietorships are both eligible; Venn does not serve Quebec, and there is no cash or cheque deposit. Open a Venn account, and see the current welcome bonus before you do.
Airwallex: Best for Many Currencies and Global Payouts
Airwallex is the account for a business that touches more than four currencies. The free Explore plan gives you local account details in 20-plus currencies to collect payments from 70-plus countries, FX at 0.5% above interbank on major currencies and 1% on the rest, free domestic CAD and USD transfers, free batch transfers to 120-plus countries on local rails (SWIFT is $20 to $35 where those rails do not exist), and unlimited Visa cards with 0% foreign transaction fees and up to 1% cash rebates on CAD spend. Bill pay and expense management are included for up to 10 users. Airwallex (Canada) International Payments Ltd is a FINTRAC-registered money services business and holds a Revenu Québec MSB licence (14460), which makes it the one fintech on this list confirmed for Quebec businesses. It is not a bank: no cash, no cheques, no lending, no CDIC coverage, and its Bank of Canada payment-service-provider registration is pending. Its published Canadian pricing lists no fee for receiving funds, but Airwallex charges 0.3% on third-party inbound transfers in other regions, so check the in-app fee schedule before routing marketplace payouts through it. Open an Airwallex account, or read the full Airwallex Canada review first.
Wise Business: Cheapest Conversions, Cleanest Transfers
Wise Business holds 22 currencies with local account details for receiving in all of them, and converts at the mid-market rate plus a transparent fee from 0.19%, the lowest headline margin on this page. There is no monthly fee, but there is a one-time 55 CAD setup charge, and receiving some currencies by wire carries a fixed fee (6.11 USD per incoming USD wire, for example; domestic CAD receipts are free). Wise now pays interest on Canadian business balances through its Interest feature, 2.22% on CAD and 3.14% on USD as of September 2026, paid monthly. The trade-offs as a primary account: no bill-pay workflow built for Canadian rails and no corporate card programme to speak of, so it works best as a conversion and holding layer beside your operating account rather than instead of one.
Loop: Best for Card Spend Across Currencies
Loop gives every plan free USD, EUR and GBP accounts alongside CAD, and its differentiator is the card: purchases in CAD, USD, EUR or GBP carry 0% FX because the charge settles from the matching balance. Converting between your own balances costs 0.47% on the free Basic plan, 0.27% on Loop Plus ($79 a month) and 0.12% on Loop Power ($299 a month). Basic includes 2 physical and 20 virtual cards earning points on CAD spend, and Loop leans further into credit than the others, with corporate card limits that suit inventory-heavy businesses. E-commerce sellers who spend heavily on US ad platforms and suppliers are the natural fit.
The Big 5 USD Account: When You Still Want One
Every major bank offers a US dollar business account, and it solves only half the problem. RBC's is typical: $9 USD a month, waived when the minimum daily balance stays above $2,500 USD, plus $1.25 USD per debit or credit. You can hold USD, but the account is domiciled in Canada, so US customers usually still pay by wire or cheque rather than ACH, and the moment you convert, the spread is typically 2.5% or more built into the exchange rate. Keep one if you deposit cash or cheques or need the lending relationship; route your actual FX through a fintech account.
The FX Math That Decides It
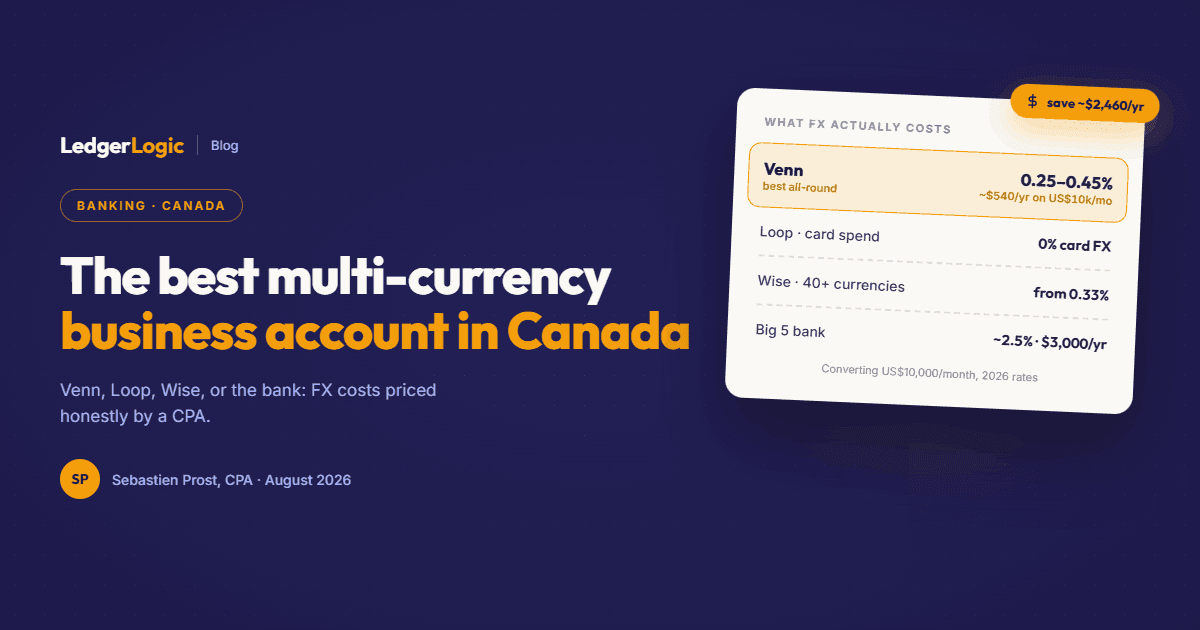
Take a business converting US$10,000 a month. At a 2.5% bank spread that is about $3,000 a year in silent FX cost. The same volume through Venn at 0.45% costs about $540, through Airwallex at 0.5% about $600, and through Wise at 0.19% about $230. Any of the three saves roughly $2,400 to $2,800 a year before counting interest earned on balances. We have seen import-heavy clients paying $15,000 to $17,000 a year in spreads without a line item ever appearing on their statements; the spread is invisible because it hides inside the exchange rate. That invisibility is exactly why this decision is worth an hour of your time.
Do You Need a USD Account or a Multi-Currency Account?
If you only receive the odd USD payment and spend everything in CAD, a simple USD account avoids double conversion and may be enough. The moment you also spend in USD (suppliers, ads, software) or touch a third currency, a true multi-currency account wins, because it lets you hold what you receive, pay from the same balance, and convert only the surplus, once, at a real rate. If your third currency is one of GBP or EUR, Venn or Loop covers it; if it is anything else, Airwallex or Wise is the answer.
Which Multi-Currency Account Works in Quebec?
Quebec requires a money-services-business licence from Revenu Québec, and that rules some fintechs out. Airwallex holds one (licence 14460), so a Quebec corporation or sole proprietor can open it today. Venn states plainly on its pricing page that it is not available to businesses in Quebec. Wise and Loop publish nothing either way on their Canadian pricing pages, so confirm at signup. The Big 5 USD accounts are available across the province.
Frequently Asked Questions
- What is the best multi-currency business account in Canada?
- For most businesses outside Quebec, Venn: no monthly fees, CAD, USD, GBP and EUR with a US-domiciled USD account for ACH, FX from 0.45%, 2% interest on CAD and USD balances, and cards and bill pay in the same account. Airwallex wins once you deal in more than four currencies or pay overseas suppliers, Wise for the cheapest pure conversions, Loop for card-heavy spending, and a Big 5 account only for cash deposits or lending.
- Can a sole proprietor open a multi-currency business account?
- Yes. Venn accepts registered sole proprietorships (business number and name registration document required) alongside corporations, and Airwallex's Canadian FAQ lists a Social Insurance Number as the identifier for sole proprietors. Quebec-based businesses are the exception for Venn, which does not serve the province.
- How do I receive US ACH payments as a Canadian business?
- You need US local account details (routing and account number), which Big 5 USD accounts generally do not provide. Venn, Airwallex and Wise all issue them, so American customers pay you like a domestic supplier, with no wire fees on either side.
- Do multi-currency accounts pay interest?
- Venn pays 2% on CAD and USD balances on every plan, with a promoted rate of up to 2.75% on CAD and 3.5% on USD for a limited time as of September 2026. Wise pays 2.22% on CAD and 3.14% on USD through its Interest feature. Airwallex and Loop do not advertise interest on Canadian balances. Verify current rates at signup; promotional rates change.
- Are these accounts safe? Is my money CDIC-protected?
- Venn holds balances at Bank of Montreal, a CDIC member, insured up to $100,000 per category. Airwallex and Wise safeguard client funds under money-services-business rules rather than insuring them through CDIC. None of the fintechs is itself a chartered bank; all are regulated money services businesses using partner institutions.
- Airwallex or Wise for a Canadian business?
- Wise is cheaper to convert (from 0.19% against Airwallex's 0.5% on major currencies) and pays interest, but charges 55 CAD to set up and fixed fees to receive some currencies by wire. Airwallex costs nothing to open and adds what Wise lacks: unlimited corporate cards with 0% foreign fees, bill pay, expense management, batch payouts and Xero and QuickBooks integrations. Pick Wise if you only convert; pick Airwallex if you also want to run spend and payables from the same account.
- What does a hidden FX spread actually cost?
- A 2.5% spread on US$10,000 a month is about $3,000 a year; the same volume at 0.45% costs about $540, and at 0.19% about $230. The fee never appears on a statement because it is embedded in the exchange rate, which is why most owners underestimate it.
- Can I keep my current bank and add a multi-currency account?
- Yes, and it is the setup we recommend most often: keep the legacy account for cash, cheques, or lending, open the fintech account in minutes, and route USD receivables, supplier payments, and conversions through it. The accounts coexist; your FX bill just moves to the cheaper rail.
Not sure which fits your flow of funds? This is a thirty-minute setup conversation with real dollars attached: ask us, or start with the full business account ranking and the side-by-side business banking comparison.
Sebastien ProstCPA, Ex-CRA
Licensed CPA with 10+ years of experience, including work with the Canada Revenue Agency. Founder of LedgerLogic, a cloud accounting firm serving Canadian SMEs. Xero Certified Advisor.