Airwallex vs Venn vs Loop (2026): Which Multi-Currency Business Account for Canada?
Disclosure: this post contains affiliate links. If you sign up through one, we may earn a commission at no extra cost to you. We only recommend tools a CPA has reviewed from the vendor's own pages.
Airwallex, Venn or Loop: which multi-currency account should a Canadian business open?
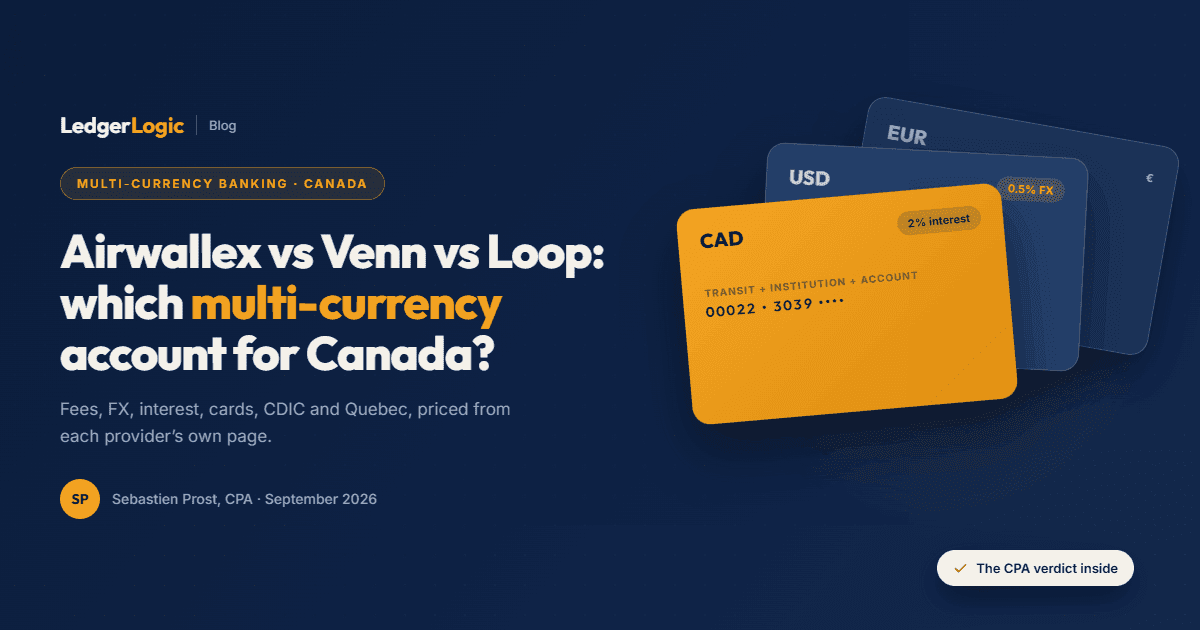
Venn for the operating account of an incorporated business or registered sole proprietor outside Quebec: $0 a month, 2% interest on CAD and USD held at Bank of Montreal with CDIC eligibility, 0.45% FX, free Interac e-Transfers, a charge card with no personal guarantee paying 1% cashback on up to $5,000 of card spend a month on the free plan, and up to $500 for registered corporations through our link. Airwallex for a Quebec business, a company collecting in many currencies, or a foreign company without a Canadian entity: $0, 20-plus currencies, 0.5% FX, a Revenu Québec licence, no interest and no CDIC. Loop for a credit card or cheaper bulk conversion: paid plans cut FX to 0.12%, its card spends a held USD, EUR or GBP balance at 0% FX (as Venn's does), wires are free, but it pays no published interest and rewards in points. Verified at all three providers, 6 September 2026; Venn rechecked 25 September 2026.
At a Glance
Airwallex, Venn and Loop are the three fintech accounts Canadian founders shortlist when a Big 5 account starts costing real money on USD. They look alike from the outside: no monthly fee, several currencies, a corporate card, a Xero or QuickBooks sync. They do different jobs, and the differences decide which one a given business should open. We run our own operating account on Venn; Venn and Airwallex pay us a referral fee, Loop pays us nothing, and every figure below comes from each provider's own pricing page rather than from a sales call.
Published September 2026. Every fee, rate and eligibility rule below was read at airwallex.com/ca, venn.ca and bankonloop.com on 6 September 2026, and the Venn figures again at venn.ca on 25 September 2026.
The Short Answer: Airwallex, Venn or Loop?
Venn for the operating account of an incorporated business or registered sole proprietor outside Quebec: $0 a month, 2% interest on CAD and USD balances held at Bank of Montreal with CDIC eligibility, 0.45% FX on the free plan, free Interac e-Transfers, and a Mastercard charge card with no personal guarantee paying 1% cashback on up to $5,000 of card spend a month on the free plan ($25,000 on Plus, uncapped on Pro), plus up to $500 for registered corporations through our link. Airwallex for the Quebec company, the business collecting in six currencies, or the foreign company that wants a CAD account before it has a Canadian entity: $0, Global Accounts in 20-plus currencies, 0.5% FX, free domestic transfers, and a Revenu Québec licence. Loop for a credit card or for converting in volume: its paid plans take FX down to 0.12%, its card spends a currency you already hold at 0% (as Venn's does), wires are free, but it pays no published interest and rewards in points rather than cash. Most businesses end up with Venn or Airwallex underneath and, if they want a credit card for heavy spending abroad, a Loop card on top.
Airwallex vs Venn vs Loop Side by Side
| Feature | Airwallex (Explore) | Venn (Essentials) | Loop (Basic) |
|---|---|---|---|
| Monthly fee | $0; Grow $12 per user plus a platform fee | $0; Plus $40; Pro $100 | $0; Plus $79; Power $299 |
| Currencies held | 20-plus, Global Accounts | CAD, USD, GBP, EUR | CAD, plus free USD, EUR and GBP accounts |
| Interest on balances | None published | 2% on CAD and USD, every plan | None published |
| FX on conversion | 0.5% major currencies, 1% others | 0.45%; 0.35% Plus; 0.25% Pro | 0.47%; 0.27% Plus; 0.12% Power |
| Card FX | Zero international fees | Spends a held USD, GBP or EUR balance first; otherwise converts at the plan rate | 0% when spending a held currency |
| Card rewards | Up to 1% rebate on local CAD spend | 1% cashback, capped at $5,000 monthly spend on Essentials | 1x points on CAD spend; 2x on Plus and Power |
| Domestic transfers | Free | $2 each on Essentials; free on Plus and Pro | Unlimited EFT, free |
| Interac e-Transfer | Received, not sent | Free | Not listed on the pricing page |
| International wires | SWIFT $20 to $35 | $10; $8 Plus; $6 Pro | Free |
| Deposit protection | None; licensed MSB, not a bank | Held at Bank of Montreal, CDIC-eligible | CAD at CDIC members to $100,000; USD at FDIC institutions to $250,000 |
| Quebec | Yes, Revenu Québec licence 14460 | No | No restriction published |
| Sole proprietors | No restriction published | Yes, registered with a business number | No restriction published |
| Accounting sync | Xero, QuickBooks Online | Xero, QuickBooks Online | Xero, QuickBooks Online |
| Offer through our link | None | Up to $500 (registered corporations) | None (not an affiliate) |
Open a $0 Venn account; corporations earn up to $500
2% interest on CAD and USD, balances at Bank of Montreal with CDIC eligibility, 0.45% FX, free Interac e-Transfers and a charge card with no personal guarantee and 1% cashback, capped by plan. Corporations and registered sole proprietors outside Quebec.
Airwallex: The Global Account That Works in Quebec
Airwallex is the only one of the three built for a business that gets paid in many currencies. The Explore plan is $0 with up to 10 Spend users and Global Accounts that collect and hold in 20-plus currencies with local account details, so a US customer pays by ACH, a UK customer by Faster Payments, and nothing converts until you choose to. FX is 0.5% above interbank on the major currencies (USD, EUR, GBP, AUD, SGD, HKD, CNY) and 1% on the rest. Domestic CAD transfers are free, international transfers to 120-plus countries are included on Explore, and SWIFT wires run $20 to $35. The Visa cards, issued by Peoples Trust, carry zero international fees and up to 1% rebate on local CAD spend. Grow is $12 per active Spend user plus a platform fee for teams that need approval workflows. Two facts settle its place on this page: Airwallex is a FINTRAC-registered money services business and holds a Revenu Québec MSB licence (14460), so it serves the Quebec companies Venn and EQ Bank turn away; and it is not a bank, so it pays no published interest and its balances are not CDIC-insured. It also opens a CAD account for a foreign company without a Canadian corporation, which no Big 5 bank will do quickly. Open an Airwallex account.
Venn: The Operating Account With Interest and CDIC
Venn (the company formerly called Vault) is the account we recommend first for incorporated Canadian businesses outside Quebec, and it is the one LedgerLogic runs its own money on. Essentials is $0 a month with CAD, USD, GBP and EUR balances, 2% interest on every CAD and USD dollar, FX at 0.45% (0.35% on the $40 Plus plan, 0.25% on the $100 Pro plan), free Interac e-Transfers, local transfers at $2 each on the free plan and free on paid plans, and international wires at $10, $8 and $6. Balances sit at Bank of Montreal and are eligible for CDIC deposit insurance, which neither Airwallex nor a card-first platform can say about a CAD operating balance in the same way. The Venn Mastercard is a charge card against the account with 1% cashback, capped at $5,000 of monthly spend on Essentials ($25,000 on Plus, unlimited on Pro), no personal guarantee and no personal credit check. Registered sole proprietors are welcome. The limits are plain: not available in Quebec, no cash or cheque deposits, no lending. Registered corporations earn up to $500 through our link (sole proprietors get the account without the bonus); the terms are on the Venn deal page. Open a Venn account.
Loop: The Credit Card and the Lowest Conversion Rate
Loop is a Toronto fintech whose product is built around the card. Basic is $0 with free USD, EUR and GBP accounts beside CAD, unlimited EFT, ACH and SEPA transfers, free wires, and FX at 0.47%; Loop Plus is $79 a month ($71 billed annually) at 0.27%, and Loop Power is $299 ($250 annually) at 0.12%, the lowest published conversion rate of the three. Its card is a Visa credit card, and like Venn's charge card it carries 0% FX when you spend a currency you already hold: an e-commerce business paid in USD that buys US ads and software on either card never converts at all. Rewards are points, 1x on CAD spend on Basic and 2x on the paid plans, rather than cash. Loop states that eligible CAD deposits are held at CDIC member institutions and protected up to $100,000, and that US operating accounts run through FDIC-insured institutions with coverage up to $250,000. It publishes no interest rate on balances and no provincial restriction. We are not a Loop affiliate and there is no offer to pass on; see Loop's pricing page for the current plans.
What Converting US$10,000 a Month Actually Costs
On the free plans the three are close: US$45 at Venn (0.45%), US$47 at Loop (0.47%) and US$50 at Airwallex (0.5%), against roughly US$250 at a Big 5 bank on its standard 2.5% spread. The gap opens on paid plans and on how you spend. A business converting US$50,000 a month pays US$225 (about CA$317) at Venn Essentials and US$60 (about CA$85) on Loop Power, so at 1.41 Canadian dollars to the US dollar, Power (with its CA$299 fee) only beats Venn Essentials above about US$64,000 of monthly conversion, and Venn Pro (0.25% for CA$100) above about US$108,600. And a business that receives USD and spends USD should not be converting at all: the Loop and Venn cards both spend a held USD balance at 0%, and an Airwallex USD balance can pay USD costs directly, which removes the fee entirely.
Interest: Venn Pays, the Others Do Not Say
This is the line that decides it for a business that keeps a cash buffer. Venn pays 2% on all CAD and USD balances on every plan; on a $150,000 operating balance that is $3,000 a year, which is more than most businesses will ever save on FX. Airwallex's Canadian pricing page publishes no interest rate and Loop's publishes none, so we treat both as paying nothing until they say otherwise. If your money sits, Venn; if it moves the day it arrives, interest matters less and the FX and card rules take over.
Who Can Actually Open Each One
Venn: corporations and registered sole proprietorships with a business number, anywhere in Canada except Quebec. Airwallex: Canadian businesses including those in Quebec, and foreign companies wanting a CAD Global Account; its Canadian pricing page states no entity-type restriction. Loop: its pricing page states no eligibility rule or provincial exclusion; confirm at signup. A Quebec corporation's realistic shortlist is Airwallex for the account and Loop for the card, with a Big 5 account kept for cash and a loan. Everyone else starts at Venn and asks whether they need either of the other two.
The Setups That Work
Canadian business, mostly CAD, some USD: Venn alone. Interest on the buffer, 0.45% when you do convert, free e-Transfers. E-commerce paid in USD, EUR or GBP: Venn or Airwallex as the operating account with local receiving details; Venn's card already spends a held USD, EUR or GBP balance at 0%, so add a Loop card only if you want a credit card for the ad spend and software in those currencies. Quebec company: Airwallex as the account, Loop as the card. Foreign company entering Canada: Airwallex, because it opens without a Canadian entity. Connect whichever you choose to Xero or QuickBooks Online; all three sync directly.
If None of the Three Fits
A business that needs cash deposits, cheques or a term loan still needs a bank; our Canadian business bank account fee index prices the Big 5 plans beside these three. For the two-way comparisons, read Venn versus Loop, Airwallex versus Wise Business and the best multi-currency business account in Canada. If cards and spend controls matter more than the account, the corporate card index puts Float, Ramp, Venn, Airwallex and Loop side by side.
Frequently Asked Questions
- Which is the best multi-currency business account in Canada?
- For an incorporated business or registered sole proprietor outside Quebec that holds and receives CAD and USD, Venn: $0 a month, 2% interest on both currencies, balances at Bank of Montreal with CDIC eligibility, and 0.45% FX on the free plan. For a Quebec business, or one collecting in many currencies, Airwallex: $0, licensed by Revenu Québec, Global Accounts in 20-plus currencies at 0.5% FX. Loop is the card to add when you want a credit card, or a conversion rate as low as 0.12% on its paid plans; both Loop's and Venn's cards spend a held currency at 0%.
- Is Airwallex available in Quebec?
- Yes. Airwallex holds a Revenu Québec money services business licence (number 14460, listed on its help-centre licensing article) alongside its FINTRAC registration, so a Quebec company can open an account. Venn states it is not available to businesses in Quebec. Loop publishes no provincial restriction on its pricing page.
- Do Airwallex, Venn or Loop pay interest on balances?
- Venn pays 2% on all CAD and USD balances on every plan, including the free one. Airwallex publishes no interest rate on its Canadian pricing page, and Loop publishes none either. On a $100,000 operating balance that is $2,000 a year at Venn and nothing stated at the other two.
- Which has the lowest FX fees?
- On the free plans, Venn at 0.45%, Loop at 0.47% and Airwallex at 0.5% on major currencies (1% on others) are within five basis points of each other: converting US$10,000 costs roughly US$45, US$47 and US$50. Paid plans open the gap: Loop Power converts at 0.12% for CA$299 a month and Venn Pro at 0.25% for CA$100. Loop also charges 0% FX when its card spends a currency you already hold, and Venn's card likewise spends a held USD, EUR or GBP balance without converting, which is the cheapest route if you receive those currencies.
- Are deposits at Airwallex, Venn and Loop protected?
- Venn balances are held at Bank of Montreal and are eligible for CDIC deposit insurance up to the applicable limits. Loop states that eligible CAD deposits are held at CDIC member institutions and protected up to $100,000, and that its US operating accounts run through FDIC-insured institutions with coverage up to $250,000. Airwallex is a licensed money services business rather than a bank, so its balances carry no CDIC coverage.
- Can a sole proprietor open Venn, Airwallex or Loop?
- Venn accepts registered sole proprietors with a business number. Airwallex serves businesses generally and does not state a sole-proprietor restriction on its Canadian pricing page. Loop does not state one either. Confirm at signup; the business number and registration document are what each will ask for.
- Is there a promo code for Venn, Airwallex or Loop?
- No codes for any of the three. Venn pays up to $500 to registered corporations that open through our link, applied automatically. Airwallex and Loop run no customer offer through us at the moment, and we are not a Loop affiliate.
- Can I use two of them together?
- Yes, and it is often the right setup. Venn as the operating account (interest, CDIC eligibility, USD receivables) with a Loop credit card on top for heavy spending abroad is a pairing that suits e-commerce businesses; Venn's own card also spends a held USD, EUR or GBP balance at 0%. A Quebec company can run Airwallex as the operating account and add a Loop card the same way.
Still deciding? Read the Venn review and the Airwallex Canada review.
Sebastien ProstCPA, Ex-CRA
Licensed CPA with 10+ years of experience, including work with the Canada Revenue Agency. Founder of LedgerLogic, a cloud accounting firm serving Canadian SMEs. Xero Certified Advisor.